
First Time Car Buyer With No Credit History: Loan Options
No credit history does not mean no car loan. Discover first time car buyer with no credit history loan options, from dealer programs to online lender connections.
By Hannah Nguyen
You have saved for a down payment, picked out a reliable set of wheels, and then the finance manager asks for your credit score. You do not have one. It is a moment that stops many first time car buyer with no credit history loan options conversations before they start. The good news is that having no credit file is not the same as having bad credit, and it does not automatically lock you out of auto financing. Lenders see a blank slate as a different kind of risk, one that can be managed with the right approach, the right loan program, and a clear understanding of how the system works.
No Credit vs. Bad Credit: What Lenders Actually See
When a lender pulls your credit report and finds no score, they are not looking at a history of missed payments or defaults. They are looking at an absence of evidence. That distinction matters because it changes the conversation from damage control to verification. A bad credit borrower has a record that shows risk; a no credit borrower has a record that shows nothing. Lenders must then decide how to price that uncertainty, and many respond by requiring a larger down payment, a co-signer, or a higher interest rate to offset the unknown.
Some lenders use alternative data to fill the gap. They may look at your income stability, rent payment history, utility bills, or even how long you have held a bank account. Others rely on first time buyer programs designed specifically for applicants with thin or no credit files. The key takeaway is that no credit is a hurdle, not a wall. Understanding which lenders are comfortable with blank slates helps you avoid wasting time on banks that will automatically decline you.
It also helps to know that credit scoring models treat a thin file differently from a damaged one. A score in the 600s with negative marks tells a story of past trouble. No score at all tells a story of inexperience. Many lenders would rather train a first time buyer than rehabilitate a borrower with a history of charge offs. That is why some dealerships and online connection services actively court no credit buyers rather than avoiding them.
How to Build a Credit File Quickly Before You Apply
If you have a few months before you need the car, you can create a credit file that gives lenders something to evaluate. The goal is not to become a prime borrower overnight, but to generate a few positive tradelines that show you can handle credit responsibly. Three tools work well for this purpose, and you can often use them in combination.
- Secured credit cards: You deposit cash as collateral, and the issuer reports your on time payments to the credit bureaus. After several months, the card may graduate to unsecured status.
- Credit builder loans: A lender holds your loan amount in a savings account while you make payments. The payments are reported to the bureaus, and you receive the funds at the end of the term.
- Authorized user status: A family member adds you to an existing credit card account. Their positive payment history appears on your report, though the benefit depends on the primary cardholder's habits.
Each of these strategies takes time, usually three to six months, to produce a score. If you need a car sooner, you may need to rely on lender programs for no credit buyers rather than waiting for a score to appear. Even a short credit history can improve your options and reduce the down payment a lender requires. Combining a small secured card with a credit builder loan can create two tradelines in a single quarter, which is often enough to generate a score.
Be careful not to overdo it. Applying for several credit cards in a short window creates hard inquiries that can lower your score once it exists. Pick one or two tools, use them lightly, and pay on time. The goal is a clean, simple file that shows consistent responsibility, not a complex web of accounts that looks like you are chasing credit.
First Time Buyer Programs and Dealership Financing
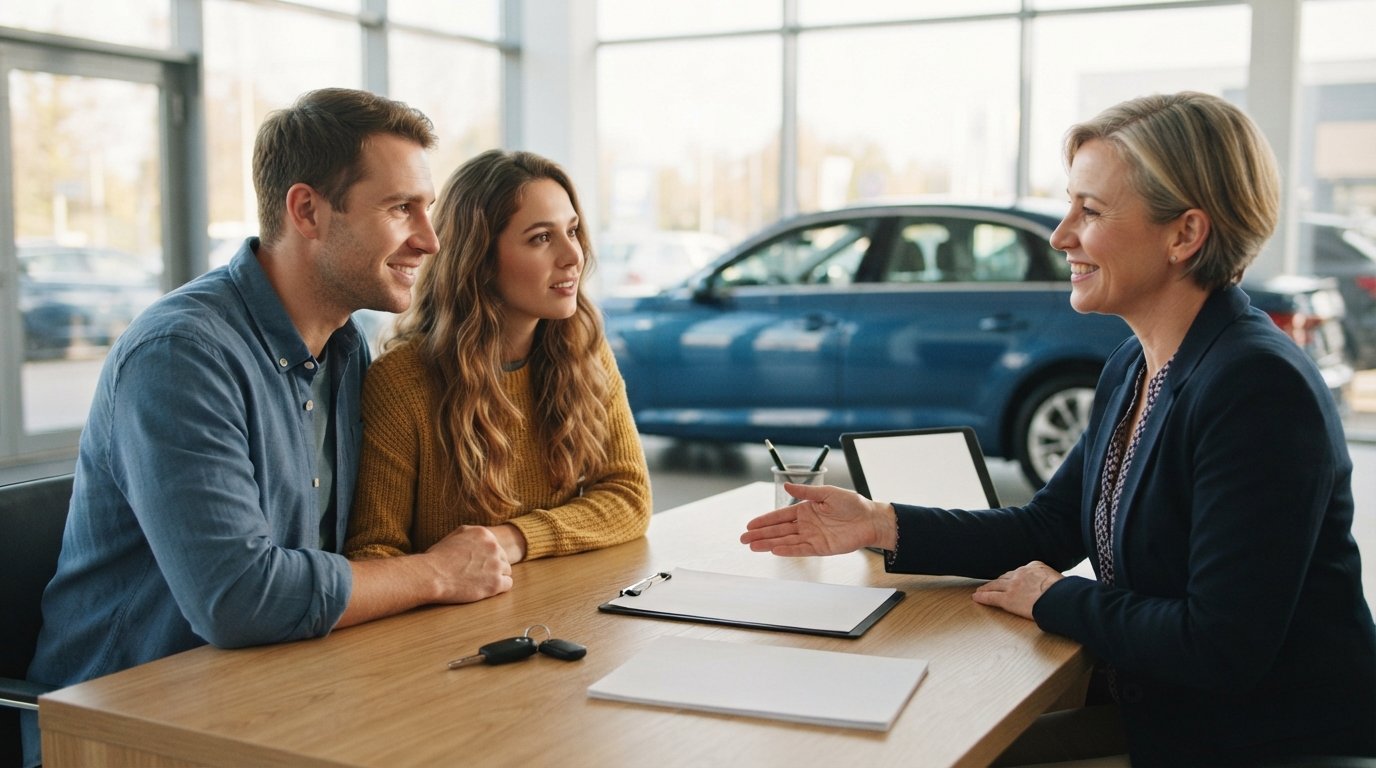
Many dealerships reserve a portion of their financing capacity for first time buyers. These programs often come with specific conditions: proof of stable income, a down payment of 10 to 20 percent, and sometimes a requirement that you finance through the dealer's preferred lenders. The advantage is that the dealer has a relationship with lenders who are comfortable with no credit files, and they can often structure a deal that a direct bank would reject. The disadvantage is that dealer arranged financing can carry a higher rate, and you may face pressure to buy add ons that inflate the total cost.
Manufacturer backed first time buyer programs are another option, particularly for new cars. These programs sometimes offer subsidized rates or down payment assistance to qualified buyers, though the definition of qualified can be strict. If you are considering a new car, it is worth asking whether the manufacturer has a college grad or first time buyer incentive. These programs can make new car financing more accessible than the sticker price suggests.
For a deeper look at how lenders evaluate applicants without a credit file, our guide on new car loans with bad credit requirements walks through the documentation and expectations that often apply to challenged credit situations. The same preparation principles apply whether your file is thin or damaged. Dealerships that specialize in second chance financing often have relationships with subprime lenders who can work with no credit buyers, but you should expect to provide more paperwork and a larger down payment than a prime borrower would.
Before you visit a dealership, ask whether they have a first time buyer program and what documents they require. Some will want proof of income, a utility bill, and references. Others will run your application through multiple lenders at once. Knowing what to bring shortens the process and signals that you are serious. It also helps you compare offers rather than accepting the first one presented.
Loan Options Designed for No Credit History Buyers
The auto loan market includes several products built for applicants who lack a traditional credit score. Understanding these options helps you ask the right questions and avoid predatory terms. The best option depends on how soon you need the car, how much you can put down, and whether you have a co-signer available.
- Dealer arranged subprime financing: The dealership works with lenders who specialize in no credit and bad credit buyers. Approval is often fast, but rates are higher and the vehicle selection may be limited.
- Buy here pay here lots: These dealers finance the car themselves, often without a credit check. They typically require a large down payment and may use payment reminder devices. The convenience comes at a cost.
- Co-signed loans: A trusted family member or friend with established credit co-signs the loan, which can secure a lower rate. The co-signer shares legal responsibility, so this option requires clear communication.
- Online connection services: Platforms that match buyers with participating lenders can streamline the process and expose you to multiple offers without visiting several dealerships.
Each option carries trade offs. Buy here pay here lots are convenient but expensive and offer little room for negotiation. Co-signed loans can save money but strain relationships if payments are missed. Dealer financing is fast but may come with add ons. Online connection services can save time but require you to read the terms carefully. A first time car buyer with no credit history loan options search should include all of these paths, not just the first one that appears.
If you are exploring online options, StartAutoLoan is an independent platform that connects consumers with lenders who work with no credit and bad credit applicants. It functions as a connection service rather than a direct lender, which means you can submit one request and compare offers from multiple participating lenders. For buyers who have been turned down elsewhere, that kind of access can be the difference between a rejection and a reasonable offer.
How AutoTitleLoan.com Connects No Credit Buyers With Lenders
AutoTitleLoan.com operates as a connection service, not a lender. That distinction is important because it means the site does not make credit decisions or set loan terms. Instead, it collects your information and shares it with a network of participating lenders and dealers who may be able to work with your situation. For a first time car buyer with no credit history loan options can feel scarce, and a connection service expands the pool of potential lenders beyond the banks you might visit in person.
The process is straightforward. You submit a request through the site's application tool, providing basic details about your income, the vehicle you want to buy, and your down payment. Participating lenders then review your information and may contact you with offers. There is no obligation to accept any loan, and submitting a request does not commit you to a deal. That low pressure approach is useful for first time buyers who want to see what is available before making a decision.
AutoTitleLoan.com also provides educational resources for buyers who are new to the financing process. The site's no credit financing page explains what lenders look for when there is no score, and the blog covers topics like bad credit auto loans and first time buyer strategies. If you are unsure whether to apply now or wait until you have built a credit file, those resources can help you weigh the trade offs. The site's focus on consumers who have been rejected by traditional lenders makes it a natural starting point for buyers who assume they cannot get approved.
Documents and Preparation That Improve Your Approval Odds
No credit buyers often face more documentation requirements than prime borrowers. Lenders want to verify that you can afford the payment, and without a credit score they rely on other evidence. Gathering the right documents before you apply speeds up the process and shows lenders that you are organized.
- Proof of income: recent pay stubs, bank statements, or tax returns if you are self employed.
- Proof of residence: a utility bill or lease agreement in your name.
- Valid driver's license and proof of insurance.
- Down payment funds: a bank statement showing available cash.
- References: some lenders ask for personal or landlord references.
Beyond documents, your down payment size and vehicle choice affect approval odds. A larger down payment reduces the lender's risk and can offset a thin credit file. Choosing a vehicle that holds its value and fits within a reasonable price range also helps. Lenders are more willing to finance a reliable used car than a high mileage luxury vehicle that may depreciate quickly. If you can wait, saving for a 20 percent down payment can open doors that a zero down application would not.
It also helps to know your budget before you apply. Calculate the total cost of ownership, including insurance, fuel, and maintenance, not just the monthly payment. Lenders may approve you for more than you can comfortably afford, and first time buyers are especially vulnerable to stretching their budget. A realistic budget protects you from a loan that becomes a burden and helps you demonstrate responsibility to future lenders.
Mistakes to Avoid When Financing Your First Car
The excitement of buying a first car can lead to decisions that haunt you for years. One common mistake is accepting the first offer without comparing alternatives. Dealer financing can be convenient, but the rate may be higher than what an online connection service or a credit union would offer. Another mistake is skipping the pre approval step. Even a soft pre qualification gives you a benchmark and negotiating leverage.
First time buyers also fall victim to add on products that inflate the loan balance. Extended warranties, gap insurance, and paint protection can be rolled into the financing, which means you pay interest on them for the life of the loan. Some add ons are worthwhile, but they should be evaluated separately rather than accepted as part of the package. Ask for the itemized price of each product and decide whether you need it.
Finally, avoid applying to many lenders in a short period. Each application can create a hard inquiry, which may lower your score once it exists and signal desperation to lenders. Use a connection service to submit one request that reaches multiple lenders, or narrow your list to two or three carefully chosen options. The goal is a clean application process that yields a manageable loan, not a scattergun approach that leaves you with a damaged file and no car.
Building Credit After You Buy
Your first auto loan is an opportunity to build the credit history you lacked when you started. Every on time payment is reported to the credit bureaus, and a year of consistent payments can produce a score that makes your next car purchase easier. Set up automatic payments to avoid late marks, and keep the loan balance manageable relative to your income. If you can afford to pay a little extra each month, doing so reduces the total interest and shortens the loan term.
After six to twelve months of on time payments, you may be able to refinance at a lower rate. Refinancing replaces your current loan with a new one, ideally with better terms. It is worth checking whether your credit score has improved enough to qualify. A refinance can lower your monthly payment or reduce the total interest you pay, and it does not require you to buy a new car.
Keep an eye on your credit report as your file grows. Errors are common, and disputing them can improve your score. The habits you build during your first auto loan, paying on time, keeping balances low, and avoiding unnecessary inquiries, will serve you well for decades. A first car is a milestone, and the financing behind it can be the foundation of a stronger financial future if you treat it with care.
Getting approved as a first time car buyer with no credit history loan options is a matter of preparation, patience, and knowing where to look. Whether you build a credit file first, use a co-signer, or connect with lenders through a service like AutoTitleLoan.com, the path exists. Focus on the total cost, not just the monthly payment, and choose a vehicle that fits your budget. The right loan is out there, and with the right approach you can drive off the lot with confidence.