
Gap Insurance for Financed Car: Do I Need It?
Gap insurance for financed car do I need it? Learn when coverage pays off, how down payment and loan term affect risk, and how to decide with confidence.
By Maya Lawson
You just drove off the lot in a car you financed, and the dealer is offering gap insurance. Or maybe you are reviewing your loan paperwork and see it listed as an optional add-on. Either way, the question is the same: gap insurance for financed car, do I need it? The answer depends on your down payment, loan term, and the moment your car's value drops faster than your balance. For many borrowers with small down payments or long loans, gap coverage can mean the difference between a clean slate and thousands in surprise debt after a total loss. This guide breaks down exactly what gap insurance does, when it pays off, and how to decide if it belongs in your financing package.
What Gap Insurance Actually Covers (and What It Does Not)
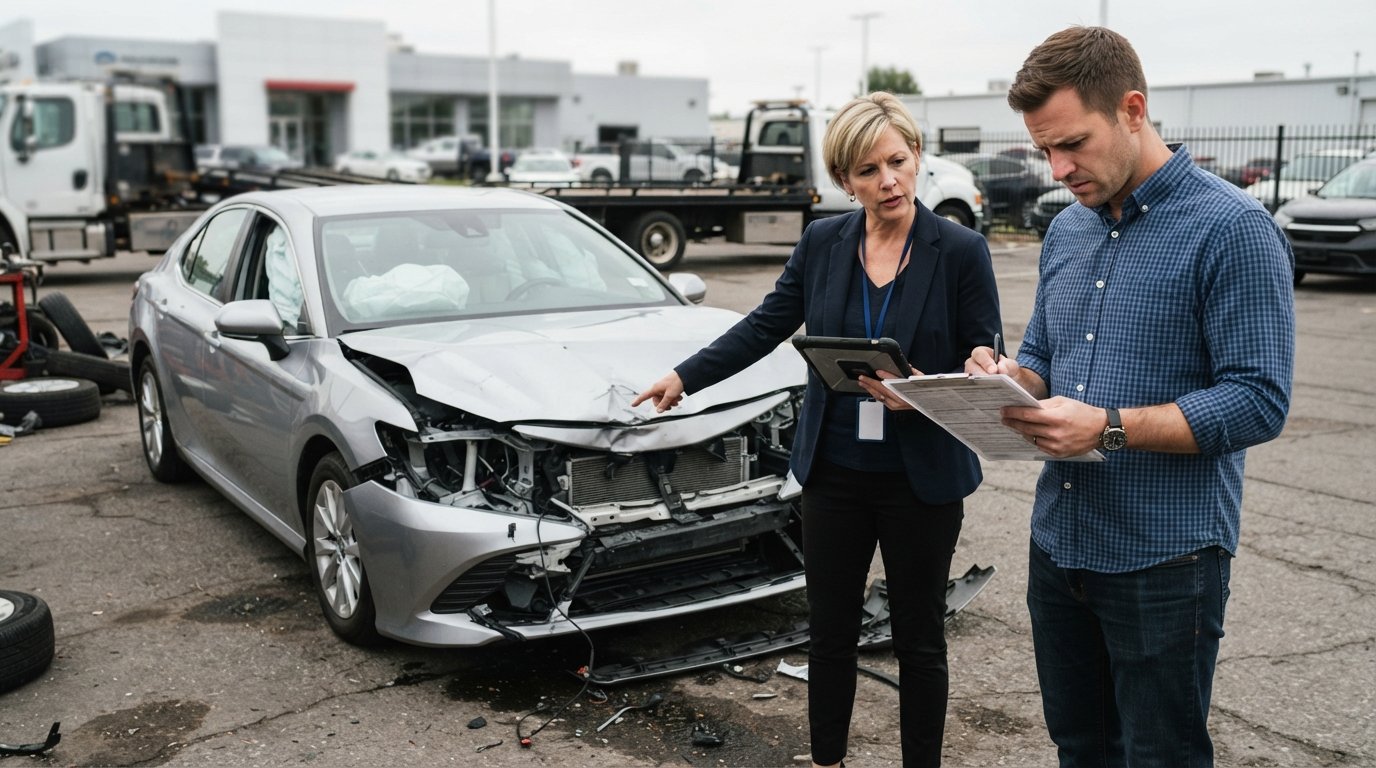
Gap insurance, short for guaranteed asset protection, covers the difference between what you owe on your car loan and what your auto insurer pays if the vehicle is totaled or stolen. Standard collision and comprehensive coverage pay actual cash value, which factors in depreciation. If you owe $22,000 but the insurer values your car at $17,000, you are left with a $5,000 gap. Gap insurance steps in to cover that shortfall, often including your deductible and any remaining loan balance, up to policy limits.
What gap insurance does not do is equally important. It does not cover negative equity you rolled into the loan from a previous vehicle, it does not pay for upgrades or aftermarket parts unless specifically included, and it does not help with missed payments or late fees. It also will not cover a down payment you hope to recover. Understanding these boundaries prevents you from buying coverage that does not match your actual risk.
Here is a quick breakdown of what gap coverage typically handles and what it leaves out:
- Covered: The difference between your loan balance and your insurer's actual cash value payout after a total loss.
- Covered: Your collision or comprehensive deductible, up to the policy limit.
- Covered: The remaining balance on the original loan, not refinanced or rolled-over amounts.
- Not covered: Negative equity carried over from a prior vehicle loan.
- Not covered: Late fees, missed payments, or extended warranty costs.
If you have ever wondered whether gap insurance for financed car do i need it, the answer starts with understanding this coverage boundary. Gap insurance is a debt-protection product, not a vehicle-protection product. It protects your finances, not your car. That distinction matters because it shapes every decision that follows.
When Gap Insurance Is Worth It (and When It Is Not)
Gap insurance delivers the most value when your loan balance is likely to exceed your car's value for an extended period. That happens most often when you put little or no money down, finance for 60 months or longer, buy a vehicle that depreciates quickly, or roll negative equity into the new loan. In these scenarios, a total loss in the first two or three years could leave you owing thousands on a car you can no longer drive.
Consider a typical example. You finance $28,000 for 72 months with no down payment. After 18 months, you have paid down roughly $6,000 in principal, leaving a balance near $22,000. If the car is totaled and the insurer values it at $16,500, you face a $5,500 gap. Without gap insurance, that amount becomes an unsecured debt you must repay out of pocket, often while also shopping for a replacement vehicle. With gap coverage, the policy pays the difference and you walk away owing nothing on the old loan.
On the other hand, gap insurance may not be necessary if you made a substantial down payment of 20 percent or more, financed for a short term like 36 months, or drive a vehicle that holds its value exceptionally well. In those cases, your loan balance drops below the car's value quickly, and the coverage may never pay out. If you are unsure which side of the line you fall on, reviewing your amortization schedule against projected depreciation can clarify your risk.
Here is a simple framework to decide whether gap coverage fits your situation:
- Compare your down payment to the vehicle price. Less than 20 percent down increases your gap risk.
- Check your loan term. Terms of 60 months or longer keep you upside down longer.
- Research depreciation for your specific make and model. Some vehicles lose value faster than others.
- Review your insurance deductible and payout history. A high deductible raises your potential gap.
Running through these four steps takes about fifteen minutes and gives you a much clearer picture than a dealer's sales pitch. If two or more factors point toward a long negative equity period, gap insurance is likely worth the cost.
How Your Down Payment and Loan Term Change the Math
The relationship between down payment, loan term, and negative equity is the heart of the gap insurance decision. A larger down payment immediately reduces the amount you finance, which means depreciation has less room to outpace your balance. A shorter loan term forces faster principal reduction, so you reach the break-even point sooner. Combine a small down payment with a long term and you create the perfect conditions for a persistent gap.
Lenders and dealers know this math well. That is why some lenders require gap insurance when the loan-to-value ratio is high or when the borrower has a limited credit history. A required gap policy is not a scam; it protects the lender's collateral position as much as your finances. If gap coverage is presented as mandatory, ask whether it is a lender requirement or a dealership policy, and compare the cost to what your auto insurer would charge for similar coverage.
For borrowers with challenged credit, the stakes can be higher. Higher interest rates mean more of each payment goes toward interest rather than principal, which slows your equity build. If you are working through credit challenges and considering financing options, platforms like StartAutoLoan can connect you with lenders who understand these situations and can help you compare offers, including how gap coverage fits into the total cost. Understanding your loan structure before you sign is the best defense against unnecessary add-ons and surprise debts.
Do Lenders Require Gap Insurance on Financed Cars?
Most lenders do not require gap insurance, but some do under specific conditions. Requirements vary by lender, loan-to-value ratio, credit profile, and vehicle type. A borrower with excellent credit and a 30 percent down payment will rarely see a gap requirement. A borrower with a high loan-to-value ratio, a long term, or a limited credit history may find gap coverage written into the loan conditions.
Even when gap insurance is not required, dealers often present it as a standard part of the financing package. It is usually optional, and you can decline it. You can also purchase gap coverage separately from your auto insurer, often at a lower cost than the dealer's price. Comparing both options before you finalize the loan gives you leverage and prevents overpaying for coverage you may not need.
If you are navigating a Chapter 13 repayment plan, financing a car involves additional considerations that affect how add-on products like gap insurance are treated. Our guide on car loans during Chapter 13 explains how trustee approval and court requirements can shape your financing choices, including optional coverage decisions.
How to Decide if Gap Insurance Belongs in Your Loan
Deciding on gap insurance comes down to a simple risk assessment: what is the likelihood that your loan balance will exceed your car's value during the coverage period, and could you afford to pay that difference out of pocket if the worst happened? If the answer to the first question is high and the second is no, gap coverage is a reasonable purchase. If you have strong equity from day one and a healthy emergency fund, you can likely skip it.
Cost is another factor. Dealer gap coverage can run several hundred dollars, sometimes rolled into the loan where it accrues interest. Auto insurers often offer loan/lease gap coverage as a low-cost endorsement, sometimes just a few dollars per month. Before you agree to any gap product, get a quote from your insurer and compare it to the dealer's offer. The coverage terms are often similar, but the price difference can be significant.
Finally, remember that gap insurance is not a substitute for emergency savings. It is a targeted tool for a specific risk. If you are already stretched thin, adding gap coverage to your loan increases your monthly payment and the total interest you pay. If you are considering financing options through a connection service, ask about how add-on products affect the loan terms and whether they can be removed to lower your payment. There is no obligation to accept any loan offer, and that includes optional coverage bundled into the deal.
Gap insurance for a financed car is not a one-size-fits-all answer. It is a calculated decision based on your down payment, loan term, vehicle depreciation, and financial cushion. Review the numbers, compare quotes, and choose the option that protects you without stretching your budget. When you understand the math, you can answer the question for yourself with confidence and drive away knowing your finances are covered.