
What Documents Do I Need for a First Time Car Loan?
Gather these documents for a first time car loan to speed approval and avoid delays. Know exactly what lenders need before you apply.
Getting your first car loan feels like a big step, and the paperwork can seem overwhelming. But here is the good news: lenders are not asking for a secret stash of documents. They just need to confirm who you are, that you can repay the loan, and that the vehicle is properly insured. Knowing exactly what to gather before you apply can turn a stressful process into a smooth one. Whether you have no credit history, a thin file, or a past bankruptcy, having the right documents ready shows lenders you are serious and organized. This guide walks you through the exact paperwork you will need, how to handle special situations, and how to submit everything through a connection service like AutoTitleLoan.com that works with lenders who specialize in first-time buyers.
The Core Documents Every First-Time Borrower Needs
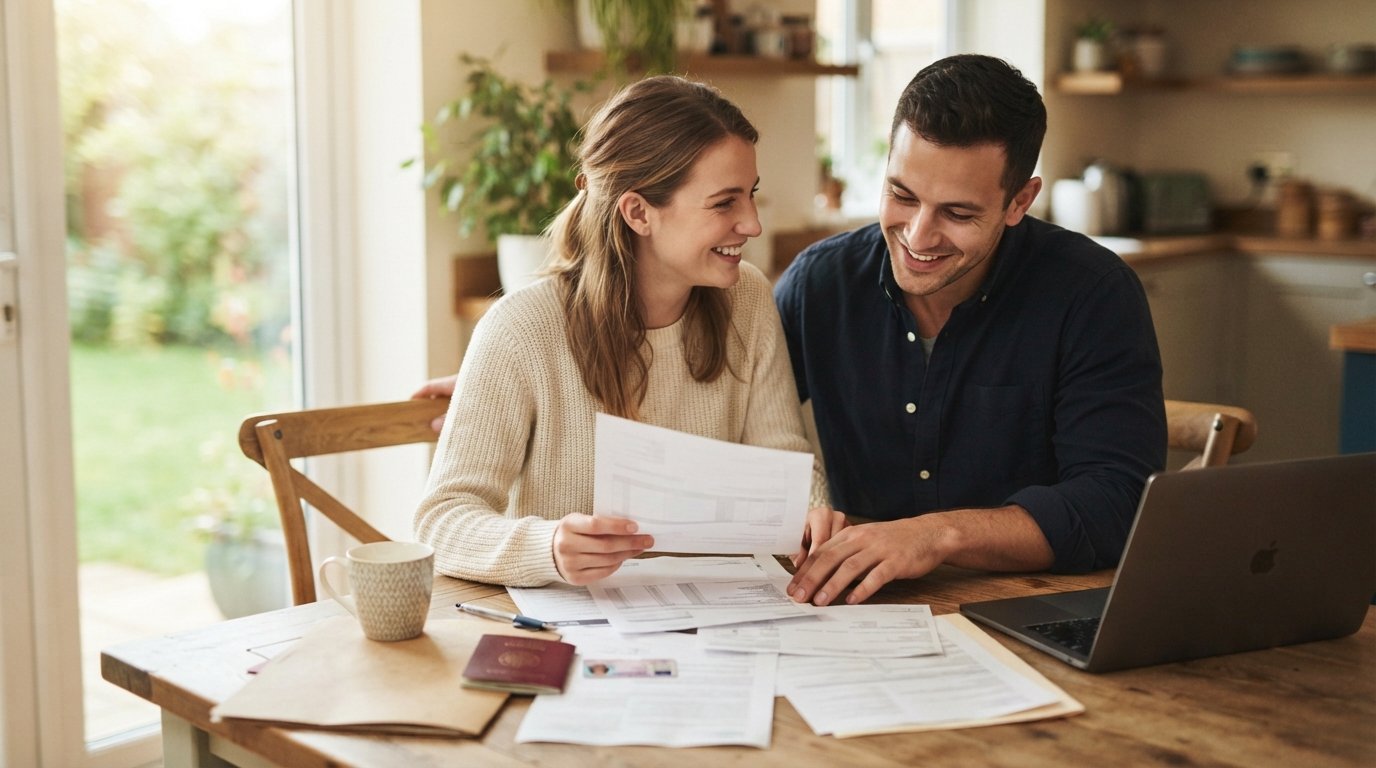
When you ask, "what documents do I need for a first time car loan," the answer starts with four basics: identification, proof of income, proof of residence, and proof of insurance. Lenders use these to verify your identity, calculate how much you can afford, confirm you live where you say you do, and protect their investment in the vehicle. Missing even one of these can delay your application or cause a rejection, so gather them early. Below is a breakdown of each category and what specifically counts as acceptable proof.
- Government-issued photo ID: A valid driver's license, state ID card, or passport. Some lenders may also accept a military ID.
- Proof of income: Recent pay stubs (usually the last 30 days), W-2 forms, tax returns, or bank statements showing direct deposits. If you are self-employed, you may need additional documentation.
- Proof of residence: A utility bill, lease agreement, mortgage statement, or bank statement with your current address, typically dated within the last 60 days.
- Proof of insurance: A current auto insurance card or policy declaration page. Some lenders require full coverage before you drive off the lot.
These four items form the foundation of almost every auto loan application, whether you are buying from a dealer or a private seller. Lenders may also ask for a down payment receipt or a purchase agreement, but those come later in the process. For now, focus on getting clear, legible copies of each document. Digital copies are usually fine, but keep paper originals handy in case a lender asks for verification.
Special Considerations for No Credit History or a Thin File
If you have never had a credit card or loan, you have what lenders call a thin credit file or no credit history. This does not automatically disqualify you, but it does mean lenders will look for alternative ways to assess your reliability. They may ask for additional documents that show consistent income and responsible financial habits. Being prepared with these extra items can strengthen your application and improve your chances of approval, especially with lenders who specialize in first-time buyers.
Here are documents that can help when your credit file is thin or nonexistent:
- Proof of alternative payments: Receipts for rent, utilities, phone bills, or insurance payments made on time over the past 12 months.
- Employment verification: A letter from your employer stating your position, length of employment, and salary, or recent offer letters if you just started a job.
- Bank statements: Three to six months of statements showing regular deposits and a positive balance can demonstrate financial stability.
- Co-signer information: If you have a co-signer, you will need their ID, income proof, and credit information as well.
These documents help lenders see the full picture of your financial life beyond a credit score. Many first-time buyers find success by working with a connection service that matches them with lenders experienced in no-credit situations. AutoTitleLoan.com, for example, connects applicants with a network of participating lenders and dealers who understand thin files and are willing to look at alternative evidence of creditworthiness.
How to Prepare and Submit Documents Through a Connection Service
A connection service like AutoTitleLoan.com simplifies the process by letting you submit one application and get matched with multiple lenders. But you still need to have your documents ready. Start by creating a digital folder on your phone or computer where you store clear photos or PDFs of each required item. Name the files descriptively (for example, "DriverLicense_JohnDoe.pdf" or "PayStub_Jan2026.pdf") so you can find them quickly. Before you apply, double-check that your ID is not expired and that your proof of residence shows your current address.
When you fill out the application, you will typically be asked to provide personal details and may be prompted to upload your documents. Some connection services pass your information to lenders who will then contact you directly for additional paperwork. Be ready to explain any gaps in employment or unusual income patterns. Transparency helps lenders work with you. Also, keep in mind that submitting a request through a connection service does not obligate you to accept any loan offer; it simply opens the door to options.
One common question is whether you need a down payment document. If you plan to make a down payment, having a bank statement showing those funds available can be helpful, but it is not always required upfront. The same goes for a purchase agreement or vehicle information; you will need those once you have chosen a car, but they are not part of the initial document checklist. Focus first on the core four, then add any special items for your credit situation.
Documents for Special Situations: Self-Employment, Bankruptcy, and More
Not every first-time buyer fits the standard employee profile. If you are self-employed, recently divorced, or have a past bankruptcy, you may need to provide extra documentation to satisfy lenders. Understanding these requirements ahead of time can save you from last-minute scrambling. Lenders are often willing to work with non-traditional situations, but they need proof that your income is stable and that any past financial issues are behind you.
Self-Employed Borrowers
If you work for yourself, lenders cannot rely on pay stubs. Instead, they typically ask for the last two years of personal and business tax returns, recent bank statements (usually three to six months), and a year-to-date profit and loss statement. Some may also request a letter from your accountant or a copy of your business license. These documents show that your income is consistent and sufficient to cover loan payments.
After Bankruptcy or Other Credit Events
If you have a bankruptcy in your past, you will likely need to provide the discharge papers or a copy of the bankruptcy dismissal. Lenders will want to see that the bankruptcy is resolved and that you have re-established some positive credit since then. You may also need to explain the circumstances in a brief letter. Being upfront and providing documentation can help lenders see that you are now financially responsible.
Using a Co-Signer
A co-signer can significantly improve your chances of approval, especially with no credit history. If you go this route, your co-signer will need to provide the same core documents: ID, proof of income, proof of residence, and possibly proof of insurance. Their credit history will be pulled as part of the application, so make sure they are aware and willing.
For a deeper dive into how loan terms affect your monthly payment and total cost, see our guide on car loan terms explained: 36 vs 48 vs 60 vs 72 months. It can help you decide which term length makes sense for your budget before you finalize your document package.
Frequently Asked Questions About First-Time Car Loan Documents
Even with a checklist, first-time buyers often have lingering questions. Here are answers to some of the most common ones. If you are still unsure, a connection service like StartAutoLoan can guide you through the process and connect you with lenders who can clarify their specific requirements. Remember, every lender is different, so always confirm the exact documents needed before you submit your application.
- Do I need a co-signer to get approved? Not necessarily. Many lenders work with first-time buyers and no-credit applicants without a co-signer, but having one can improve your terms.
- Can I use electronic copies of my documents? Yes, most lenders and connection services accept digital uploads or clear photos. Just make sure the text is readable and all four corners of the document are visible.
- What if I do not have a utility bill in my name? A lease agreement, mortgage statement, or a letter from your landlord may work. Some lenders also accept a bank statement with your address.
- How recent must my pay stubs be? Typically within the last 30 days. If you are paid weekly, provide the last four stubs; if biweekly, the last two.
- Will I need to show proof of insurance before getting the loan? Many lenders require proof of insurance before finalizing the loan, but you may be able to get a conditional approval first. Check with your lender.
Being prepared with the right documents is the single best way to speed up your first car loan approval. Start gathering your core four today, add any special items based on your situation, and consider using a connection service to compare offers from multiple lenders. With the paperwork in order, you can focus on the fun part: choosing your car.